Can a Mortgaged Property Qualify for Turkish Citizenship?
Learn whether mortgaged property qualifies for Turkish citizenship, how a mortgage registered on the title deed may affect the investment application, and which legal requirements to verify before applying.
Whether a mortgaged property is eligible for Turkish citizenship is one of the important questions foreign investors ask before purchasing a property in Turkey with the aim of obtaining Turkish citizenship through real estate investment.
A mortgage registered in the title deed (Tapu) may affect the possibility of transferring ownership or completing the investment procedures. However, determining whether a property is eligible does not depend solely on the existence of a mortgage. It requires verifying the nature of the mortgage, the restrictions registered against the property, and the requirements of the investment-based citizenship program.
In general, Turkish regulations require the purchase of a property worth at least USD 400,000, the registration of a restriction prohibiting its sale for three years, and compliance with the remaining legal and administrative requirements.
Turkish official authorities emphasize the need to check mortgages and restrictions that may prevent a sale before beginning the ownership transfer procedures. This helps ensure that the transaction is legally sound and avoid potential legal problems in the future.
In this article, we explain the relationship between mortgaged property and Turkish citizenship, whether Turkish citizenship can be obtained through a mortgaged property, how a mortgage affects investment eligibility, how to check the title deed, and the main reasons for rejecting a citizenship application.
Is a Mortgaged Property Eligible for Turkish Citizenship?
The answer depends on the type of mortgage, its legal implications, and whether the property meets the requirements for investment-based citizenship. It is not enough for the property to reach the required value; its legal status must also be suitable for completing the transaction and obtaining a certificate confirming that the investment requirements have been met.
Mortgaged Property and Turkish Citizenship: What Is the Relationship?
A mortgage is a legal security interest registered against a property in favor of a creditor, usually a bank, to secure repayment of a loan or another financial obligation. The property may remain registered in its owner's name despite the mortgage, but this does not mean it can be sold or transferred without taking the creditor's rights and the relevant legal procedures into account. Therefore, when assessing a property's eligibility for Turkish citizenship, three matters must be distinguished:
- Property ownership: Is the seller the registered owner in the title deed, and does the seller have the right to dispose of the property?
- Registered mortgage: Does the mortgage status allow the sale and transfer of ownership to be completed, or is the bank's approval, repayment of the debt, or another legal procedure required?
- Citizenship requirements: Does the property meet the investment value, registration, three-year non-sale restriction, and other applicable requirements?
Can You Obtain Turkish Citizenship Through a Mortgaged Property?
A mortgaged property can be assessed to determine its eligibility, but it is incorrect to assume that every mortgaged property qualifies for citizenship or that every mortgage automatically prevents eligibility. The outcome depends on the details of the transaction, the nature of the registered restriction, the possibility of completing the ownership transfer, and the competent authorities' acceptance of the property as an eligible investment.
It is important not to confuse purchasing a property that already has an outstanding mortgage with purchasing a property using new bank financing. Each situation has its own legal and financial details, and its implications for the citizenship application may differ.
Before paying a deposit or signing a binding contract, the title deed records should be checked, and the Land Registry Directorate and the authority responsible for confirming investment eligibility should be consulted to determine whether the specific situation is acceptable.
Discover how to obtain Turkish citizenship through real estate investment, and learn about the main legal requirements and procedures that can help you choose an eligible property and avoid obstacles before purchasing.
Requirements for Turkish Citizenship Through a Mortgaged Property
It is essential to distinguish between the general requirements for foreigners purchasing property and the requirements for a property to qualify for Turkish citizenship. A property may be legally available for sale but still fail to meet the requirements of the investment-based citizenship program.
Property Requirements for Turkish Citizenship
According to official information published by the Investment Office of the Presidency of the Republic of Türkiye, the basic requirements for an eligible real estate investment include the following:
- Minimum value: Purchasing an eligible property worth at least USD 400,000, based on the accepted valuation.
- Ownership registration: Registering the property or meeting the requirements applicable to a notarized promise-to-sell agreement, where relevant.
- Non-sale restriction: Undertaking not to sell the property for three years.
- Proof of investment: Submitting the required documents to obtain the investment confirmation certificate.
- Legal requirements: Ensuring that the buyer is eligible, the transaction is valid, and no restrictions prevent its completion.
These requirements do not mean that every property worth USD 400,000 automatically grants its owner citizenship. The application is subject to verification and assessment, and the granting of citizenship remains dependent on a decision by the competent authorities.
Does a Mortgage Prevent You from Obtaining Turkish Citizenship?
A mortgage should not automatically be assumed to result in the rejection of a citizenship application. Equally, its presence should not be assumed to have no effect. The key issue is the extent to which the mortgage affects the property's eligibility, the registration of the transaction, and compliance with the investment requirements.
For example, if a property is mortgaged to a bank, it may be necessary to obtain the bank's approval, repay the debt, or agree on a legal procedure that allows the sale to proceed. The required procedure must be determined by examining the mortgage agreement and title deed records rather than relying on a general assumption.
If the mortgage is connected to a dispute, an attachment, or enforcement proceedings, additional restrictions may apply. A detailed legal review is then necessary to establish whether the sale and transfer of ownership can be completed without potential legal obstacles before the purchase.
Property Mortgaged to a Bank and Turkish Citizenship
When purchasing a property mortgaged to a bank, written information should be requested about:
- The outstanding debt and the creditor.
- The conditions for releasing the mortgage or transferring ownership while the mortgage remains in place.
- Whether the property can be registered in the buyer's name.
- Whether the property's legal status is compatible with the requirements for obtaining citizenship through real estate investment.
- The documents required by the competent authority to issue a certificate confirming investment eligibility.
- The crucial point is that the bank's approval of the sale does not, by itself, mean that the property qualifies for citizenship. Likewise, the ability to register the property in the buyer's name does not automatically mean that the investment requirements have been met.
If you want to purchase property safely in Turkey, explore the types of title deeds in Turkey and their legal importance, and discover how to verify ownership and property restrictions before making an investment decision.
The Impact of a Mortgage on Turkish Citizenship and Title Deed Procedures
A mortgaged property must be legally reviewed before the purchase price is paid or the buyer commits to purchasing it. Turkish official authorities recommend checking mortgages, rights, and restrictions that may prevent a sale before starting the ownership transfer procedures.
Property with a Mortgage Registered in the Title Deed and Turkish Citizenship
The title deed record is one of the most important documents to examine before purchasing a property. The buyer should verify the type of registered restriction, the party benefiting from it, the conditions for removing it, and whether there is an attachment, a prohibition on disposal, or another right that may affect the sale.
Basic property information can be checked through the parcel inquiry portal operated by the Turkish General Directorate of Land Registry and Cadastre. However, online information does not replace obtaining the official record and reviewing detailed restrictions with the relevant directorate.
Legal Mortgages and Turkish Citizenship in Turkey
The legal implications vary depending on the type of registered restriction: a bank mortgage, a mortgage arising from a financial obligation, an enforcement attachment, or a restriction on disposal. The nature of the restriction must therefore be identified first. The existence of a mortgage does not necessarily prohibit a sale, but releasing the mortgage or obtaining the creditor's approval may be a condition for completing it.
It is also important not to confuse a mortgage with the three-year non-sale restriction required under the investment-based citizenship program. These are two different restrictions with different purposes and legal effects, and neither can be treated as a substitute for the other.
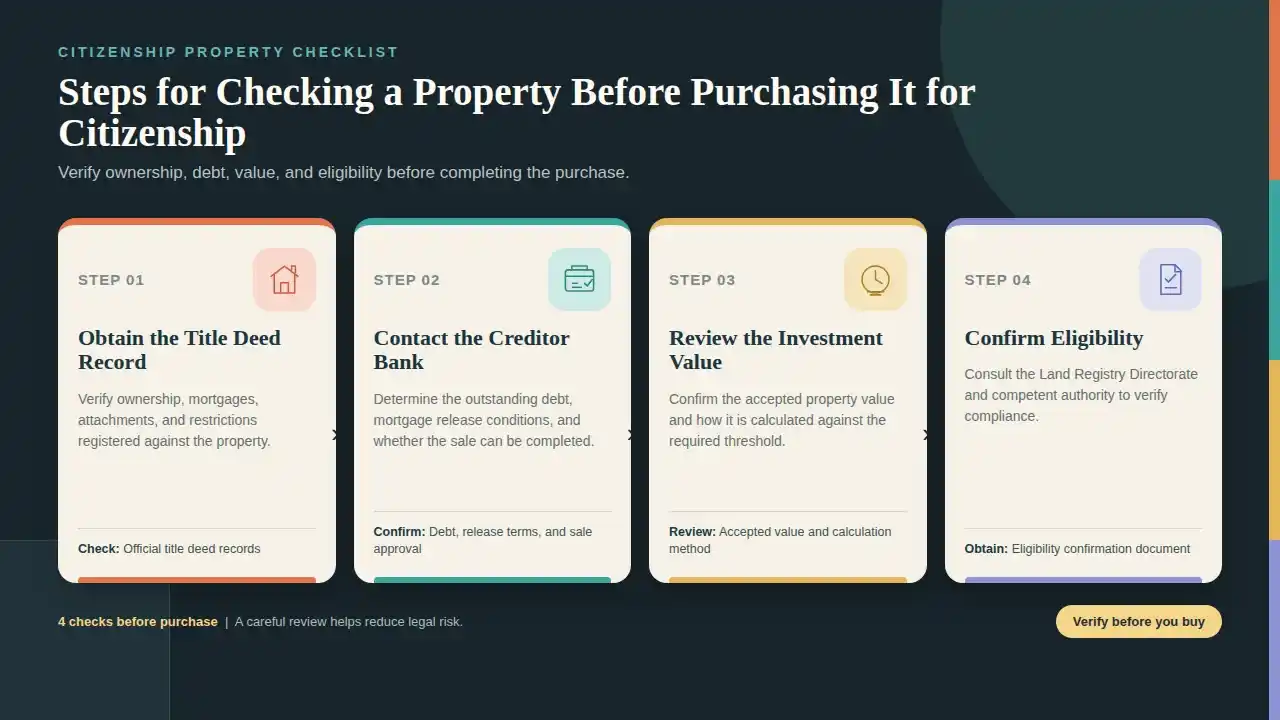
Steps for Checking a Property Before Purchasing It for Citizenship
To avoid legal problems and ensure that a mortgaged property complies with Turkish citizenship requirements, the following steps are recommended before completing the purchase:
Step 1: Obtain the title deed record: Verify ownership, mortgages, attachments, and restrictions registered against the property.
Step 2: Contact the creditor bank: Determine the outstanding debt, the conditions for releasing the mortgage, and whether the sale can be completed.
Step 3: Review the investment value: Confirm the accepted value of the property and how it is calculated against the required threshold.
Step 4: Confirm eligibility: Consult the Land Registry Directorate and the competent authority to verify compliance with the investment requirements and obtain the eligibility confirmation document.
Learn about the bank documents required for a Turkish citizenship application through real estate, and find out how to prove the investment value and financial transfers to prepare your application in accordance with the legal requirements.
Looking for a reliable real estate platform to sell your property quickly and transparently?
EmlakPlatform is not just an option, it is the smart solution for you. We combine advanced technology, full transparency, and professional support
Can Foreigners Buy a Mortgaged Property in Turkey, and What Are the Reasons for Citizenship Rejection?
Buying a mortgaged property in Turkey is legally different from purchasing a property free of restrictions. The purchase may be possible, but it may require resolving the mortgage or fulfilling the conditions associated with it. For Turkish citizenship, the transaction must also be assessed under the rules governing real estate investment.
Turkish Citizenship Through the Purchase of a Mortgaged Property
Before purchasing, the buyer should reach an agreement with the seller and the bank to repay the debt and release the mortgage, or otherwise complete the transaction lawfully. The agreement should preferably include conditions that protect the buyer if the mortgage cannot be released, the transaction cannot be registered, or the property is not accepted under the citizenship program.
It is not advisable to transfer the entire amount to the seller based solely on a verbal promise that the mortgage will be removed later. The payment method, mortgage release, and ownership transfer arrangements must be clear and enforceable, and the transaction should be reviewed by a lawyer specializing in real estate in Turkey.
Property Purchased with a Bank Loan for Turkish Citizenship
If the buyer intends to use a bank loan to finance the purchase, they should not assume that the property's value alone is sufficient to meet the investment requirement. The amount counted toward the investment, the source of funds, the payment method, the financing terms, and the restrictions registered against the property must all be checked. Two situations must be distinguished:
- Purchasing a property that already has a mortgage: The mortgage is registered in favor of a creditor, and the sale may require that this restriction be addressed.
- Purchasing a property using bank financing: A mortgage may be registered in favor of the financing bank, and the transaction must be checked for compliance with the citizenship requirements.
General information is not sufficient to establish that both situations will be accepted. The final assessment depends on the details of the transaction and the rules applied by the competent authorities.
Learn how the real estate valuation report affects a Turkish citizenship application, and discover which conditions must be checked to ensure that the property's value is counted toward an eligible investment.
Reasons for Rejection of Turkish Citizenship Through Real Estate
A transaction may be rejected or its procedures may not be completed if the required conditions are not met. The main risks that should be checked include:
- Failure to meet the applicable minimum investment value.
- A problem with ownership registration or the buyer's eligibility to own the property.
- A mortgage, attachment, or restriction that prevents completion of the required transaction.
- Failure to meet the requirements for registering the three-year non-sale restriction.
- Discrepancies or problems in payment documents, valuation reports, or proof of investment.
- Failure to meet regulatory requirements relating to the type of property or the method of purchase.
- Failure to obtain the certificate confirming that the investment requirements have been met, or failure to complete the remaining stages of the citizenship application.
The guidance of the Turkish Land Registry Directorate emphasizes that issuing a certificate confirming investment eligibility does not automatically grant citizenship. The citizenship application remains subject to assessment and a decision by the competent authority.
Explore the guide to choosing the right property for Turkish citizenship through real estate ownership, including the main legal and investment criteria that can help you make an informed decision.
Table Explaining the Eligibility of Mortgaged Property for Turkish Citizenship by Situation
| Property situation | What should be checked? | Initial assessment |
| Property free of a mortgage | Value, registration, and the remaining investment requirements | May be eligible if all requirements are met |
| Property mortgaged to a bank | Whether the sale can be completed, how the mortgage will be addressed, and whether the transaction will be accepted | Requires a specific review |
| Property purchased with a new bank loan | Financing and payment arrangements and the effect of the new mortgage on eligibility | Requires prior official confirmation |
| Property subject to an enforcement attachment | Whether disposal is prohibited and whether the attachment can be lifted | Requires careful legal review |
| Mortgaged property with an agreement to release the mortgage | Repayment arrangements, timing, and procedures for cancellation and registration | Depends on implementation of the agreement and acceptance of the transaction |
| Property that does not meet the minimum value | Accepted valuation and whether other eligible properties can be counted | Does not meet the requirement on its own if the counted value is below the required threshold |
| Property that meets the value requirement but lacks a non-sale restriction | Whether the required restriction can be registered in accordance with the applicable rules | Does not meet all requirements until the outstanding conditions are completed |
Frequently Asked Questions About Mortgaged Property and Turkish Citizenship
Not necessarily. The type of mortgage, the possibility of completing the property transfer, and compliance with all investment citizenship requirements must be verified. Eligibility cannot be confirmed solely by knowing whether the property is mortgaged or mortgage-free.
Not every mortgage automatically disqualifies a property. However, it may affect eligibility if it prevents the sale or conflicts with the applicable regulatory requirements. The registered encumbrance and the relevant authority should be consulted before purchasing the property.
This depends on the details of the mortgage and whether the transaction can be completed in accordance with the applicable rules. Before committing to the purchase, you should clarify the bank's conditions, determine the procedures for releasing or otherwise addressing the mortgage, and obtain confirmation that the property can be accepted under the citizenship program.
The general minimum investment amount for qualifying real estate is USD 400,000, subject to compliance with registration requirements, the restriction prohibiting the sale of the property for three years, and all other official conditions. Meeting the value threshold alone does not guarantee that citizenship will be granted.
You should obtain the official title deed registry record and check for mortgages, attachments, and other restrictions. Consult the creditor bank when necessary, review the valuation and payment documents, and request confirmation from the Land Registry Directorate and the authority responsible for verifying the investment. It is advisable to consult a specialized lawyer before making a payment or signing a binding contract.
Conclusion: Is a Mortgaged Property Eligible for Turkish Citizenship?
Answering the question of whether a mortgaged property is eligible for Turkish citizenship requires examining the property's legal status and the entire transaction, rather than relying solely on its value or the existence of a mortgage in the title deed.
An eligible real estate investment for Turkish citizenship must meet the minimum value requirement, be registered in the legally required manner, comply with the three-year non-sale restriction, obtain proof that the investment requirements have been met, and complete the remaining citizenship procedures.
A property mortgaged to a bank, or one purchased using a bank loan, must be examined separately to determine whether the transaction can be completed and officially accepted under Turkish citizenship requirements and the applicable regulations.
Therefore, the best way to protect your investment is to verify the title deed record, the mortgage conditions, the payment arrangements, and the property's eligibility with the competent authorities before signing the contract or transferring funds.